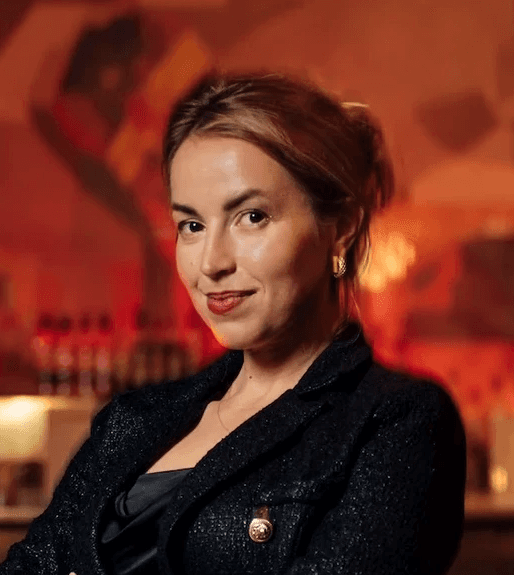
The idea that Europe is regulating itself out of competitiveness has become a familiar refrain. It surfaces in policy debates and boardrooms alike, often as a simple explanation for why the continent lags behind the United States in technology. But according to Anu Bradford, Henry L. Moses Professor of Law and International Organization at Columbia Law School, that diagnosis misses the point.
“The debate about digital regulation is a sideshow to the main problems underlying Europe’s technical system.”
Bradford does not dismiss the importance of competitiveness. On the contrary, she frames it as fundamental. “There’s no security without prosperity. Europe needs more economic growth, and technology is key to that.”
But focusing on regulation, she argues, risks distracting from deeper structural constraints that have shaped Europe’s tech ecosystem for years.
A fragmented market at home
The most immediate of these constraints is internal fragmentation. Despite decades of integration, Europe remains far from a seamless market.
“There’s no true digital single market in Europe. We still have a very fragmented marketplace.” For companies, this makes scaling fundamentally different from the United States. Instead of expanding within one large market, European firms must navigate many.
“European tech companies have to scale across 27 different markets, with different languages, consumer preferences, and regulatory fragmentation.”
The cost of this fragmentation is not abstract. “If you translate those internal barriers into tariff equivalents, it’s about 60% for goods and close to 100% for services.”
These are not formal tariffs, but they illustrate how difficult it is to operate across Europe as if it were a single market.
Why scaling remains difficult
Bradford zeroes in on four issues that explain why this competitiveness problem persists: market fragmentation, capital, risk culture, and talent.
She has already pointed to fragmentation as a core constraint. Capital is another. “European companies do well in early funding rounds, but when they need larger amounts of capital, they often turn to US investors or get acquired.”
Risk culture also plays a role. “In Europe, if you fail, you’re often done. It’s very hard to raise money again.”
She contrasts this with the United States. “In the US, failure is part of the model. After bankruptcy, investors may still back you if you’re working on something ambitious.”
Talent flows reinforce the gap. “Europe is losing talent to the US, where the capital, top universities, and concentration of talent are.”
Taken together, these factors describe a system where innovation exists, but scaling remains constrained.
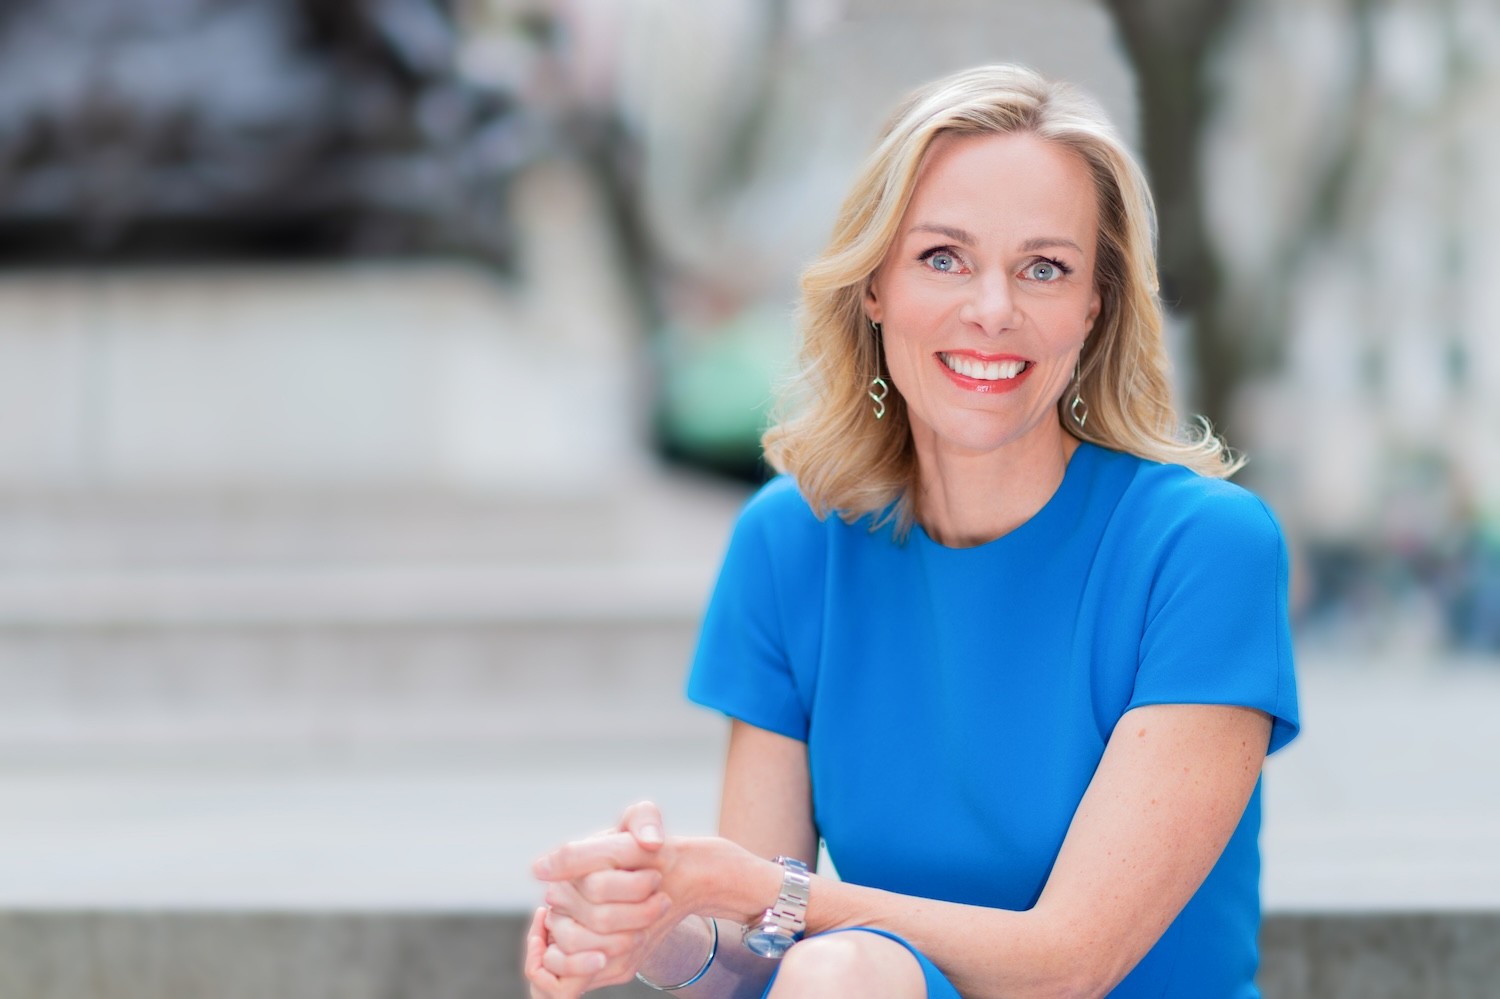
Anu Bradford is the Henry L. Moses professor of law and international organization at Columbia Law School and director of its European Legal Studies Center. Her research focuses on international trade law, EU law, and antitrust.
A world without a dominant model
The global environment is also shifting. The expectation that one model of technology governance will prevail is fading.
“There won’t be a single regulatory model that becomes global.” Bradford explores this dynamic in Digital Empires, where she outlines competing American, Chinese, and European approaches to regulating technology.
In the interview, she notes that each model faces its own pressures. “They’re all having a moment, but also facing headwinds.”
The result is not convergence, but coexistence.
The rise of tech sovereignty
For companies, this fragmentation is already reshaping strategy.
“Tech companies are now expected to offer sovereign solutions, where governments retain control over data and operations.”
Meeting those expectations often requires duplication. “That means replicating infrastructure, like building data centers in different parts of the world.”
Global operations are becoming less uniform and more complex, as firms adapt to political and regulatory demands.
Leaders as geopolitical actors
This environment is changing what leadership requires.
“Leaders need to understand geopolitics. In many ways, they have to become diplomats.”
Executives are no longer navigating markets alone. Regulation, security concerns, and political expectations increasingly shape strategic decisions.
Bradford also emphasizes the importance of consistency. “You need to be agile, but also clear about your principles. Companies need to communicate who they are and how they make decisions.”
Europe’s unfinished agenda
Amid global complexity, Bradford returns to Europe’s internal challenges. “The digital single market should be the number one priority.”
She also highlights the need to improve how regulation is implemented. “We need to avoid overlaps and inconsistencies.”
The issue, in her view, is not whether Europe regulates too much, but whether it has built the conditions that allow companies to scale. For Nordic firms, the implications are direct. Their home markets are small, making European scale essential, yet difficult to achieve.
This question of scale also shapes how Bradford views the AI debate. She pushes back against the idea of it as a race to be won. “There won’t be a single country or company that wins the AI race.”
Instead, she shifts the focus to where value is created. The more important question is not who builds the most advanced models, but who applies them effectively. The real gains come from adoption and use, not necessarily just from dominating the underlying technology.
What emerges is a more complex environment, where competitiveness depends on structural reform at home and the ability to navigate a fragmented global system.
·
5 min read
The idea that Europe is regulating itself out of competitiveness has become a familiar refrain. It surfaces in policy debates and boardrooms alike, often as a simple explanation for why the continent lags behind the United States in technology. But according to Anu Bradford, Henry L. Moses Professor of Law and International Organization at Columbia Law School, that diagnosis misses the point.
“The debate about digital regulation is a sideshow to the main problems underlying Europe’s technical system.”
Bradford does not dismiss the importance of competitiveness. On the contrary, she frames it as fundamental. “There’s no security without prosperity. Europe needs more economic growth, and technology is key to that.”
But focusing on regulation, she argues, risks distracting from deeper structural constraints that have shaped Europe’s tech ecosystem for years.
A fragmented market at home
The most immediate of these constraints is internal fragmentation. Despite decades of integration, Europe remains far from a seamless market.
“There’s no true digital single market in Europe. We still have a very fragmented marketplace.” For companies, this makes scaling fundamentally different from the United States. Instead of expanding within one large market, European firms must navigate many.
“European tech companies have to scale across 27 different markets, with different languages, consumer preferences, and regulatory fragmentation.”
The cost of this fragmentation is not abstract. “If you translate those internal barriers into tariff equivalents, it’s about 60% for goods and close to 100% for services.”
These are not formal tariffs, but they illustrate how difficult it is to operate across Europe as if it were a single market.
Why scaling remains difficult
Bradford zeroes in on four issues that explain why this competitiveness problem persists: market fragmentation, capital, risk culture, and talent.
She has already pointed to fragmentation as a core constraint. Capital is another. “European companies do well in early funding rounds, but when they need larger amounts of capital, they often turn to US investors or get acquired.”
Risk culture also plays a role. “In Europe, if you fail, you’re often done. It’s very hard to raise money again.”
She contrasts this with the United States. “In the US, failure is part of the model. After bankruptcy, investors may still back you if you’re working on something ambitious.”
Talent flows reinforce the gap. “Europe is losing talent to the US, where the capital, top universities, and concentration of talent are.”
Taken together, these factors describe a system where innovation exists, but scaling remains constrained.
Anu Bradford is the Henry L. Moses professor of law and international organization at Columbia Law School and director of its European Legal Studies Center. Her research focuses on international trade law, EU law, and antitrust.
A world without a dominant model
The global environment is also shifting. The expectation that one model of technology governance will prevail is fading.
“There won’t be a single regulatory model that becomes global.” Bradford explores this dynamic in Digital Empires, where she outlines competing American, Chinese, and European approaches to regulating technology.
In the interview, she notes that each model faces its own pressures. “They’re all having a moment, but also facing headwinds.”
The result is not convergence, but coexistence.
The rise of tech sovereignty
For companies, this fragmentation is already reshaping strategy.
“Tech companies are now expected to offer sovereign solutions, where governments retain control over data and operations.”
Meeting those expectations often requires duplication. “That means replicating infrastructure, like building data centers in different parts of the world.”
Global operations are becoming less uniform and more complex, as firms adapt to political and regulatory demands.
Leaders as geopolitical actors
This environment is changing what leadership requires.
“Leaders need to understand geopolitics. In many ways, they have to become diplomats.”
Executives are no longer navigating markets alone. Regulation, security concerns, and political expectations increasingly shape strategic decisions.
Bradford also emphasizes the importance of consistency. “You need to be agile, but also clear about your principles. Companies need to communicate who they are and how they make decisions.”
Europe’s unfinished agenda
Amid global complexity, Bradford returns to Europe’s internal challenges. “The digital single market should be the number one priority.”
She also highlights the need to improve how regulation is implemented. “We need to avoid overlaps and inconsistencies.”
The issue, in her view, is not whether Europe regulates too much, but whether it has built the conditions that allow companies to scale. For Nordic firms, the implications are direct. Their home markets are small, making European scale essential, yet difficult to achieve.
This question of scale also shapes how Bradford views the AI debate. She pushes back against the idea of it as a race to be won. “There won’t be a single country or company that wins the AI race.”
Instead, she shifts the focus to where value is created. The more important question is not who builds the most advanced models, but who applies them effectively. The real gains come from adoption and use, not necessarily just from dominating the underlying technology.
What emerges is a more complex environment, where competitiveness depends on structural reform at home and the ability to navigate a fragmented global system.
Nordic Listed Leaders Board Programme
Learn board work from
the people who do it.
Harvard cases, coaching and open dialogue with people who sit on and work with boards of Finnish publicly listed companies.
Next cohort
19 November 2026
Then January, April, August and October 2027


Latest on Listeds

